IGCR non-compliance means breaking any condition of the Customs (Import of Goods at Concessional Rate of Duty or for Specified End Use) Rules, 2022 after you have imported goods at a concessional rate. The concession is conditional, so a breach turns the duty you saved back into a debt, with interest, and exposes the goods to confiscation and you to a penalty.
The Rules were notified by Notification No. 74/2022-Customs (N.T.) dated 9 September 2022 and replaced the IGCR Rules, 2017. They were last amended by Notification No. 07/2025-Customs (N.T.), which from 2 February 2025 moved returns to a quarterly cycle and gave importers one year, instead of six months, to use the goods where the notification sets no period. Many older guides still quote the 2017 position.
What Counts as IGCR Non-Compliance
Customs treats any of the following as IGCR non-compliance, whether it is deliberate or a missed deadline:
Not using the goods for the specified end use within the permitted period
Not filing the quarterly statement in Form IGCR-3 by the due date
Diverting goods to trading, resale or a use the notification does not cover
Sending goods to a job worker and not bringing them back, or not accounting for them, within the job work period
Not reporting non-receipt or short receipt of goods in Form IGCR-2
Not keeping the Rule 6 records of receipt, consumption, job work, re-export and stock
Clearing unused goods without paying the duty and interest, or re-exporting them below their import value
The first two are the ones that catch most importers. They are also the easiest to prevent.
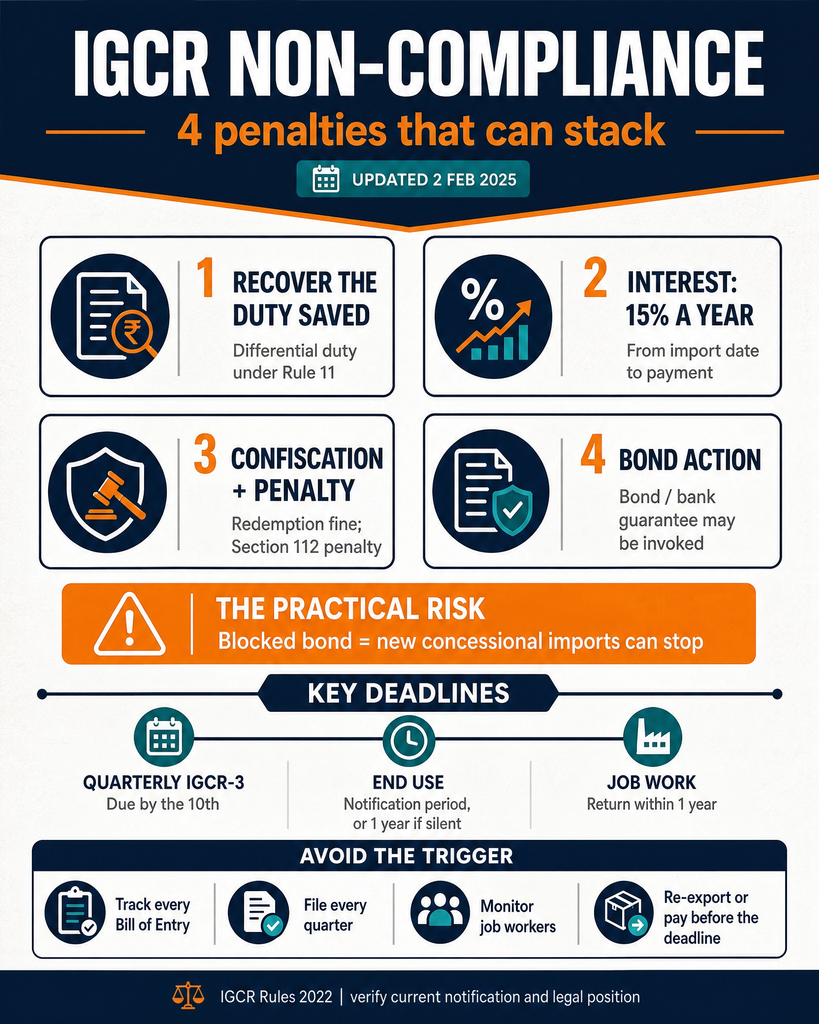
The 4 Penalties for IGCR Non-Compliance
The consequences stack. One breach can trigger all four.
Penalty
Legal basis
What it costs you
1. Recovery of the duty saved
Rule 11, IGCR Rules 2022
The full differential duty on the goods concerned
2. Interest
Section 28AA, Customs Act 1962 (rate 15% a year)
Runs from the date of import to the date you pay
3. Confiscation and penalty
Sections 111(o), 112 and 125
Goods liable to confiscation, a redemption fine, and a penalty of up to 10% of the duty involved or Rs 5,000, whichever is higher
4. Penalty under the Rules and bond action
Rule 12 read with Section 158(2)(ii); Rule 4(3) bond
A separate penalty for the contravention, plus invocation of the bond and any bank guarantee
1. Recovery of the duty you saved
Under Rule 11 the jurisdictional Deputy or Assistant Commissioner invokes your continuity bond and recovers the differential duty, which is the duty at the standard rate minus the duty you actually paid. For goods imported under a notification that is not an exemption, the bond covers an amount equal to the assessable value instead.
2. Interest at 15% a year
Interest is charged at the rate notified under Section 28AA, currently 15% a year, from the date of import until the date of payment. If Rs 2,00,000 of duty was forgone and the shortfall is found 12 months after import, the interest alone is about Rs 30,000.
3. Confiscation, redemption fine and penalty
Section 111(o) makes goods liable to confiscation where they were exempted subject to a condition and the condition was not observed. In practice the goods are usually released on a redemption fine under Section 125, and a penalty under Section 112 follows: for dutiable goods, up to 10% of the duty sought to be evaded or Rs 5,000, whichever is higher.
4. A penalty under the Rules and action on the bond
Rule 12 adds a penalty under Section 158(2)(ii) for any contravention by the importer or the job worker, without affecting other action. Separately, the bond stays debited until you account for the goods. Once the bond balance is used up, your next Bills of Entry cannot claim the concession, which is often the most expensive consequence for a factory running on imported inputs.
One correction to what many sites say: the IGCR Rules 2022 do not contain a power to suspend your IIN. The practical block on future imports comes from the bond and from recovery action, not from a suspension clause.
IGCR Timelines You Must Meet
Most IGCR non-compliance starts with a missed date. These are the deadlines as amended from 2 February 2025:
Obligation
Deadline
Where it comes from
Use the goods for the specified end use
The period in the notification, or one year from import if none is given
Rule 10 (six months before 2 February 2025)
Extension of the end-use period
Up to 3 more months, for reasons beyond your control
Rule 10 proviso, granted by the jurisdictional Commissioner
Quarterly statement in Form IGCR-3
By the 10th day of the month after each quarter (10 April, 10 July, 10 October, 10 January)
Rule 6(2)
Goods with a job worker
Back within one year of the invoice or e-way bill
Rule 7(3) (six months before 2 February 2025)
Non-receipt or short receipt
Immediately, in Form IGCR-2
Rule 6
Unused or defective goods
Re-export at no less than import value, or clear on payment of duty and interest
Rule 10
The full filing process for the statement is in our guide to the IGCR monthly return, which explains why it is now quarterly.
What Happens If You Miss an IGCR Timeline
The two timelines fail in different ways.
Missing the end-use period. The concession on those specific goods is treated as unmet. You pay the differential duty with interest, and the amount is secured against the bond. It applies only to the goods that missed the window, not to your whole import history.
Missing a quarterly statement. The statement is how you prove consumption and get the bond re-credited. Without it your consumption is unproven and the bond stays debited. If goods are then not shown as used within the end-use period, recovery follows on those goods. ICEGATE also expects every quarter to be filed in order, so one missed quarter holds up the ones after it, including quarters with no activity.
The real risk is that these compound: an unfiled statement blocks the bond, a blocked bond stops new concessional imports, and data checks on declared inputs against output can then open a wider enquiry.
How to Avoid IGCR Non-Compliance
Keep a register of every Bill of Entry under your IIN with its import date and end-use deadline
Diary the four quarterly dates and file on time, even for a quarter with no activity
Use Form IGCR-3A during the quarter if you need the bond re-credited sooner
Track goods sent to job workers against the one-year limit
If goods will not be used, re-export them or pay the duty and interest before the period ends, not after a demand arrives
Keep consumption records that match your production data
What to Do If You Have Already Missed a Deadline
Act quickly. File any pending quarterly statements in order so the record is current. Where goods have gone past the end-use period, pay the differential duty and interest on those goods voluntarily; Rule 10 allows clearance of unused goods on voluntary payment, which is far better than waiting for a demand and a penalty. If the delay was beyond your control and the period has not yet run out, ask the jurisdictional Commissioner for an extension before it does. For older periods filed on ICEGATE 1.0, reconcile the bond balance with your jurisdictional officer.
How JPARKS INDIA Helps
We manage the whole IGCR cycle so that non-compliance never builds up: IGCR-1 filing, bond and security, end-use tracking per Bill of Entry, quarterly IGCR-3 and IGCR-3A filing, and clean-up of missed periods. JPARKS INDIA is backed by S.K. Agency, AEO-LO customs brokers since 1990. See our IGCR clearance service, email [email protected] or call +91 91673 79073.
Frequently Asked Questions
Q1. What is the penalty for IGCR non-compliance?
You repay the duty you saved with interest at 15% a year, the goods become liable to confiscation with a penalty under Section 112, and Rule 12 adds a further penalty under Section 158(2)(ii). The bond and any bank guarantee can be invoked.
Q2. How long do I have to use goods imported under IGCR?
The period stated in the notification, or one year from the date of import if the notification is silent. The jurisdictional Commissioner can extend it by up to three months for reasons beyond your control.
Q3. Is the IGCR return monthly or quarterly?
Quarterly since 2 February 2025. Form IGCR-3 is due by the 10th of the month after each quarter.
Q4. Can Customs suspend my IIN for IGCR non-compliance?
The IGCR Rules 2022 have no suspension clause. The practical block comes from a debited bond and recovery action, which stop you claiming the concession on new imports.
Q5. What if my goods cannot be used in time?
Re-export them at a value not below their import value, or clear them on voluntary payment of the duty and interest, before the period ends.
Q6. Do I need to file a statement for a quarter with no imports?
Yes. ICEGATE expects a statement for every quarter in sequence, including quarters with no activity.
Need this handled for you?
Tell us where you are stuck. We usually reply the same business day.
5.0 ★ · 123 Google reviews · Since 1990
Posted on Google
Vandana Bajaj
Trustindex verifies that the original source of the review is Google.
Very prompt and reliable service by Rahul Kolge and his team. Exceptional and happy experience.
Posted on Google
Supriya Shetye
Trustindex verifies that the original source of the review is Google.
Had a really good experience with JParks India. Rahul sir helped me a lot with my import work and were always active and responsive. Whatever documents or guidance was needed, they handled everything smoothly and explained things clearly. Felt stress-free throughout the process. Very helpful team, definitely recommend them if you’re doing import or export.
Posted on Google
dipali sakpal
Trustindex verifies that the original source of the review is Google.
Very nice people, get the work done in a very short time.
Posted on Google
Satish Bajaj
Trustindex verifies that the original source of the review is Google.
Excellent & Prompt services in all Import Export matters.
Great to work with you
Posted on Google
Bajaj VCPL
Trustindex verifies that the original source of the review is Google.
It was a great experience having work with you.
Posted on Google
Satish Bajaj
Trustindex verifies that the original source of the review is Google.
"Outstanding professiona services, efficient, and gets things done incredibly fast. Highly recommended for anyone needing reliable and prompt assistance
Posted on Google
Nishat fatima
Trustindex verifies that the original source of the review is Google.
excellent service
Posted on Google
farhan sayed
Trustindex verifies that the original source of the review is Google.
JParks Team is Super helpful! Thanks to Rahul and team!
Posted on Google
Sadik Inamdar
Trustindex verifies that the original source of the review is Google.
Good and personal service for import export code
Posted on Google
Maheshwar
Trustindex verifies that the original source of the review is Google.
Had a really good experience with JParks India. Rahul sir helped me a lot with my import work and were always active and responsive. Whatever documents or guidance was needed, they handled everything smoothly and explained things clearly. Felt stress-free throughout the process. Very helpful team, definitely recommend them if you’re doing import or export.
Verified by Trustindex
Trustindex verified badge is the Universal Symbol of Trust. Only the greatest companies can get the verified badge who has a review score above 4.5, based on customer reviews over the past 12 months. Read more
We use cookies to run this site, measure traffic, and track our ads. Essential cookies are always on. Accept all, reject non-essential, or set your preferences.
Cookie Preferences
Manage your cookie preferences below:
Essential cookies enable basic functions and are necessary for the proper function of the website.
Name
Description
Duration
Cookie Preferences
This cookie is used to store the user's cookie consent preferences.
30 days
Google reCAPTCHA helps protect websites from spam and abuse by verifying user interactions through challenges.
Name
Description
Duration
_GRECAPTCHA
Google reCAPTCHA sets a necessary cookie (_GRECAPTCHA) when executed for the purpose of providing its risk analysis.
179 days
Google Tag Manager simplifies the management of marketing tags on your website without code changes.
Name
Description
Duration
cookiePreferences
Registers cookie preferences of a user
2 years
td
Registers statistical data on users' behaviour on the website. Used for internal analytics by the website operator.
session
Statistics cookies collect information anonymously. This information helps us understand how visitors use our website.
Google Analytics is a web analytics service that tracks and reports website traffic. It collects anonymized data on how visitors use the site to help us understand and improve performance.